
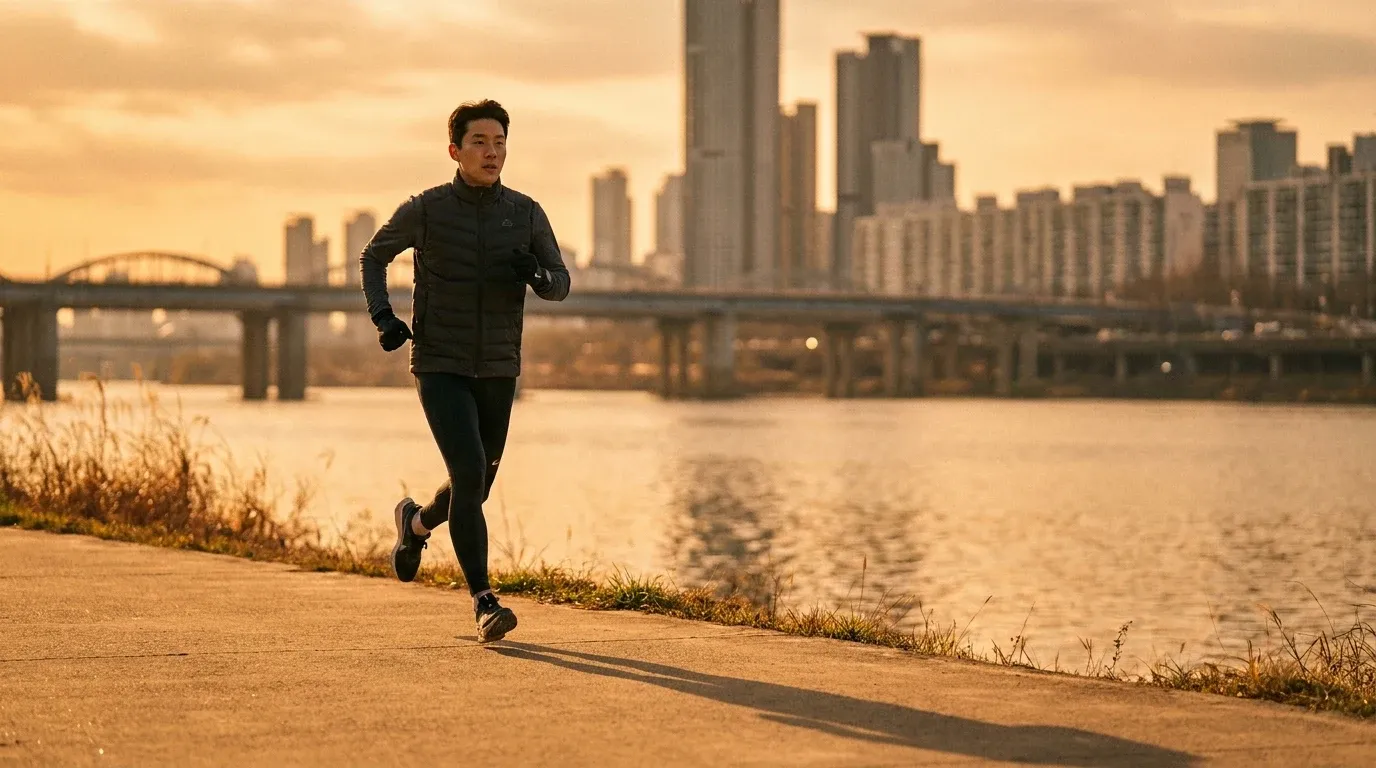
South Korea crossed a significant threshold in September 2026: 10 million active runners. That number isn't just a headline. It's a market-intelligence signal that Asia-Pacific running culture has reached a scale where seasonal product cycles, category preferences, and distribution strategies need to be rethought by every global sports brand with ambitions in the region.
The autumn surge in running gear searches and sales that followed this milestone tells you something specific about where the opportunity sits. It's not just volume. It's timing, category mix, and price-tier complexity that brands operating in Europe or North America will recognize. Asia-Pacific is no longer a lagging market. It's running on its own seasonal clock now, and that clock matters for your product drops, your wholesale calendar, and your inventory positioning.
The Autumn Spike: What Korean Runners Are Actually Buying
As temperatures drop across the Korean peninsula from late September through November, search and sales data from major Korean retail platforms and global e-commerce indexes shows a sharp pivot toward cold-weather running gear. Windbreakers, thermal long-sleeve tops, running gloves, and temperature-regulating footwear all register meaningful search volume increases, mirroring the autumn running gear cycles observed in Germany, the UK, and the northeastern United States.
What's distinct about the Korean product mix is the emphasis on layering precision and wind protection over heavy insulation. Korean runners are predominantly urban. They're running along the Han River pathways, through city parks, and on treadmills in building gyms. Their thermal needs sit in a specific range: cold enough for wind-resistant outer layers, not cold enough for the heavy insulated jackets that drive autumn sales in Scandinavian or Canadian markets.
This creates a clear category priority list for brands targeting Korean autumn demand:
- Lightweight windbreakers in the $80–$160 range with packability and reflectivity features
- Thermal long-sleeve base layers with moisture-wicking properties, priced between $45 and $90
- Running gloves with touchscreen compatibility, a functional requirement for Korean runners who monitor pace and heart rate data closely
- Transitional footwear with slightly higher stack heights or thermal sock compatibility, as Korean runners rarely switch to full winter-specific shoes
Brands that drop autumn collections without accounting for this specific layering logic risk inventory misalignment. Heavy puffer running jackets and chunky thermal footwear that move well in Nordic markets will underperform in Seoul. Precision matters more than insulation depth.
10 Million Runners Changes the Distribution Math
There's a threshold effect that happens when a running market scales past a certain size. Below it, premium performance products are the primary commercial opportunity because the consumer base skews toward dedicated athletes who will invest in technical gear. Above it, mass-market running products become viable at scale alongside those premium lines, and the distribution picture bifurcates.
Korea at 10 million active runners has crossed that threshold. You're now looking at a market where a mid-tier running shoe at $100–$130 can move meaningful volume through general sporting goods retail, while a $220 carbon-plated performance shoe simultaneously finds its audience through specialty run stores and brand direct-to-consumer channels. Both can coexist profitably, but they require different channel strategies, different inventory depths, and different marketing approaches.
For wholesale buyers sourcing for Korean retail, this bifurcation creates a real planning challenge. Allocating too heavily toward premium performance SKUs underserves the growing mass-market runner who joined the sport in the last two to three years and hasn't developed brand loyalty yet. Over-indexing on mass-market product leaves performance-oriented runners who drive disproportionate spend per transaction underserved at the specialty tier. The brands winning in Korea right now are running both strategies in parallel with clean channel separation.
The broader parallel to watch is what happened in the US running market between 2012 and 2018, when participation growth pushed mass-market running into mainstream sporting goods retail while simultaneously deepening the specialty channel. Korea is compressing that evolution into a shorter window, which means brands that move fast on channel strategy will capture disproportionate early share.
Korea Within the Asia-Pacific Expansion Story
Korea's 10 million runner milestone doesn't exist in isolation. It's part of a broader Asia-Pacific sports apparel and footwear expansion that market analysts consistently identify as the highest-growth geography for sports brands through the late 2020s. The region is projected to account for a growing share of global sports apparel revenue, with running-specific categories outpacing overall athleisure growth as participation data from Japan, Australia, and Southeast Asian urban centers all trend upward.
What Korea offers that other markets in the region don't is a combination of high digital retail penetration, strong domestic brand culture, and a consumer base that responds to international brand positioning. Korean runners are active on platforms where they follow global running culture, research gear, and share performance data. They're not isolated from global product conversations. That makes Korea an effective test market for autumn running collections before broader Asia-Pacific rollouts.
This regional growth dynamic connects directly to adjacent categories. As Asia-Pacific running culture matures, demand for performance nutrition, hydration technology, and recovery tools scales alongside it. The innovation happening in hydration monitoring, for instance, as seen with companies like those covered in our reporting on Nix Biosensors closing $10M in Series A funding to scale hydration tech, reflects the kind of performance infrastructure investment that follows maturing running markets. Korean runners who are tracking pace and heart rate are increasingly aware of hydration and fueling data too.
The sports nutrition market context is equally relevant here. As documented in the analysis of where growth is concentrated in the $93.8B sports nutrition market in 2026, Asia-Pacific represents one of the fastest-growing regional segments for performance nutrition spending. Running market growth and nutrition market growth in the region are correlated, and brands operating across both categories have an opportunity to build compound presence.
Timing Product Drops to Korea's Seasonal Rhythm
The practical implication for brand operators is calendar-level precision. Korean autumn running gear demand spikes in late September and peaks through October. That's consistent enough across multiple years of search data to treat as a reliable seasonal pattern. Your drop timing for windbreakers and thermal layers should hit Korean retail and DTC channels in the first two weeks of September at the latest, allowing inventory to be visible before search volume peaks.
Contrast this with the European autumn running cycle, which often peaks slightly later in October, and the North American market, where the seasonal shift varies significantly by geography. Korea's autumn window is concentrated and relatively short before winter conditions push training indoors. Missing the peak window by even two to three weeks means missing a meaningful percentage of seasonal conversion opportunity.
Regional product drops timed to Korean seasonal patterns also offer a differentiation signal to Korean consumers. When a global brand acknowledges the Korean autumn running window with specific product launches or regional availability, it communicates market understanding. Korean consumers, particularly in running communities, respond positively to brands that treat their market as a primary audience rather than a spillover from other regional strategies.
What the Running Boom Tells You About Korean Consumer Behavior
Running's growth in Korea isn't random. It accelerated through a combination of urban infrastructure investment in running-friendly public spaces, strong social media running culture, and a documented shift toward individual fitness activities that gained momentum post-2020. Korean runners skew younger than the average running market in Western countries, with significant participation in the 25–39 age bracket. This demographic is highly digitally connected, brand-aware, and willing to invest in gear that signals both performance intent and aesthetic quality.
That combination of performance focus and aesthetic sensitivity is important for product development teams. It's why technical features alone don't close the sale in the Korean market. Color execution, silhouette quality, and brand visual identity carry real weight alongside technical specs. Brands that treat Korea purely as a performance gear market without investing in product presentation will find conversion rates disappointing relative to the scale of the opportunity.
The running culture dimension also has training behavior implications. Korean runners are disproportionately engaged with structured training, pace tracking, and community running events. Understanding that the Korean runner is often a data-oriented, socially connected participant helps brands think about what content and product positioning actually lands. Coverage of training science, like research showing that 3 minutes of sprinting produces comparable molecular adaptations to 90 minutes of steady cardio, resonates with this audience precisely because they're looking for optimization frameworks, not just motivation.
Similarly, content that bridges fitness performance with longevity and everyday activity science, such as findings that 3 minutes of daily activity cuts cardiovascular risk significantly, reflects the health-conscious framework that many Korean urban runners operate within. They're not just training for race times. They're investing in long-term physical capital, and gear purchasing decisions follow that logic.
The Strategic Takeaway for Brands
Korea's 10 million runner milestone is a concrete signal that Asia-Pacific running markets have matured to a point where Western-style seasonal product strategy is not just applicable but necessary. The autumn gear surge is real, it's measurable, and it follows a pattern brands can plan against with confidence.
Your response to this signal should operate on three levels. First, adjust your drop calendar to capture Korea's concentrated autumn demand window in September and October. Second, audit your category mix for the Korean market to ensure windbreakers, thermal layers, and accessory categories are adequately stocked relative to heavier insulation product. Third, build distribution strategies that serve both the mass-market runner entering the sport and the performance-oriented runner who drives premium category growth.
The brands that treat Korea as a leading indicator for Asia-Pacific seasonal strategy rather than a secondary market will be positioned ahead of the curve when the rest of the region follows the same maturation pattern. The data is already pointing in that direction. The question is whether your product calendar is.