
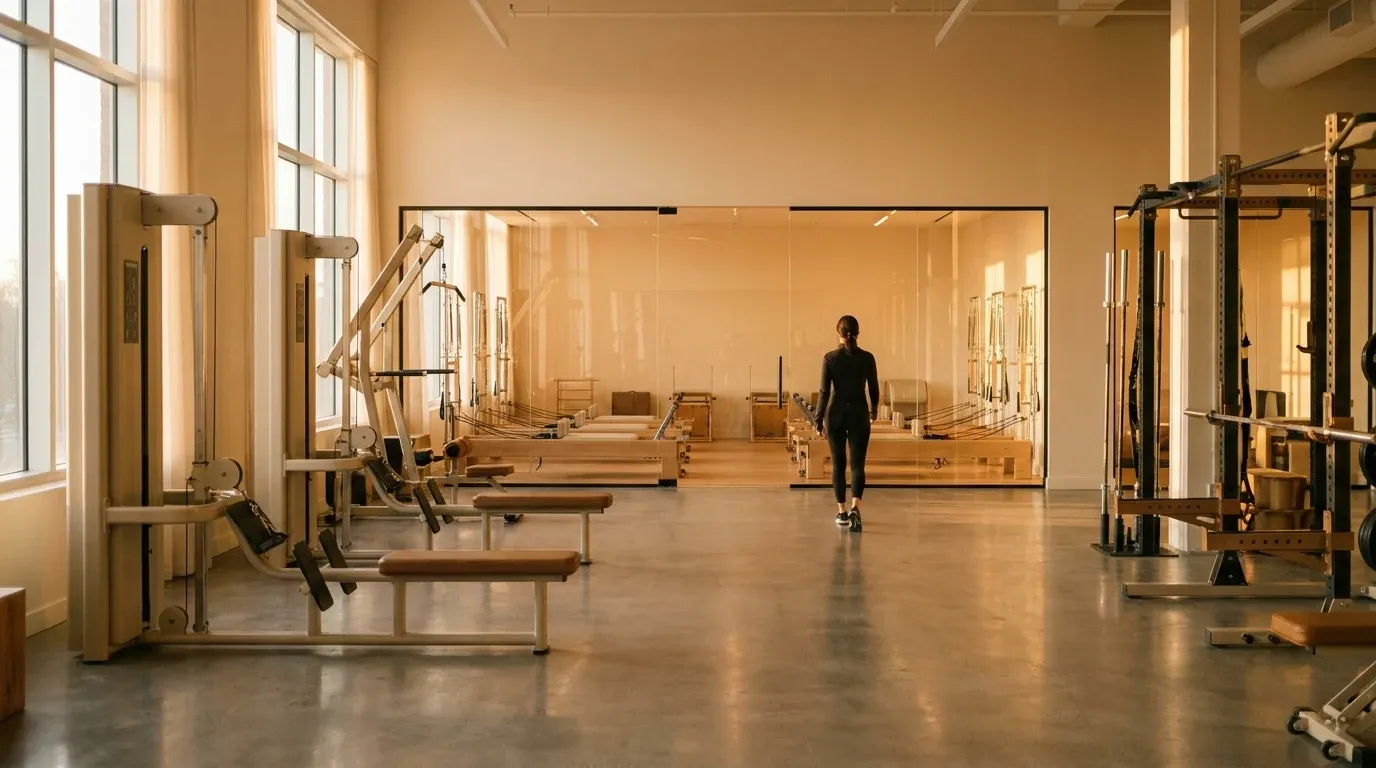
Denver is quietly becoming a live laboratory for the most ambitious structural bet in franchise fitness right now. Fit Fusion, a multi-unit Crunch franchisee, is rolling out four new Crunch 3.0 locations across the Denver metro area. Each one will embed the operator's own Reform Pilates boutique concept directly inside the larger club footprint. That's not a marketing refresh. It's a capital allocation thesis.
If it works, it rewrites the unit economics playbook for big-box gym operators. If it doesn't, it becomes an expensive case study in what happens when two distinct consumer segments share a roof.
What the Crunch 3.0 Format Actually Is
Crunch 3.0 isn't just a cosmetic update to the brand's existing layout. It represents a deliberate shift toward boutique-style specialization housed inside a traditional high-square-footage club. The model is engineered to compete on two fronts simultaneously: against low-cost chains like Planet Fitness on volume and accessibility, and against premium studio operators like Club Pilates or Pure Barre on experience and retention.
That dual positioning is harder to execute than it sounds. Low-cost chains win on price compression and operational simplicity. Premium studios win on instructor quality, intimacy, and programming depth. A hybrid format has to deliver enough of both without diluting either.
Fit Fusion's answer is the embedded boutique. Rather than treating Pilates as an add-on class in a group fitness room, the operator is building out a dedicated Reform Pilates studio as a distinct revenue unit within each location. Members can access the main club floor on standard membership terms. The Pilates component operates on its own pricing and scheduling structure.
The Unit Economics You Need to Understand
The financial logic here is worth unpacking carefully, because it's the variable that will determine whether other franchisees follow Fit Fusion's lead.
Standard big-box gym floor space generates revenue primarily through membership dues spread across a high member-to-square-foot ratio. The model depends on low utilization rates: most members don't show up most of the time, which is why the numbers work. Boutique studio space inverts that logic. A Reformer Pilates studio with 12 to 14 machines generates revenue per session, per person, at rate cards that typically run $30 to $40 per class at the independent level, or $180 to $220 per month on unlimited membership packages in the US market.
The buildout cost for a dedicated Reformer studio inside an existing big-box footprint runs roughly $150,000 to $300,000 depending on equipment count, flooring, sound isolation, and HVAC requirements. That's before instructor payroll, which is the ongoing cost variable most operators underestimate. Qualified Reformer Pilates instructors in major US metros currently command $40 to $65 per hour, and you need consistent fill rates across multiple daily sessions to service the debt on that buildout while covering labor.
Break-even math on an embedded boutique studio typically requires class fill rates above 70 percent across peak and off-peak sessions. That's achievable in a high-density urban market with strong brand positioning. In a suburban Denver location competing against established boutique operators, it's a real test of local marketing execution and member conversion from the main floor.
For a broader breakdown of where the US gym market stands and what operators are doing to maintain margins in a maturing membership environment, the operator playbook for 77 million US gym members outlines the key strategic responses to slowing growth across the sector.
Why Now: The Market Window Argument
The timing of Fit Fusion's Denver expansion isn't arbitrary. The global health club market is projected to grow from $131.31 billion in 2025 to $244.70 billion by 2032. That's a near-doubling of addressable revenue in seven years, driven by rising health consciousness, aging demographics with disposable income, and post-pandemic normalization of gym attendance as a lifestyle baseline rather than an aspirational behavior.
What that projection also signals is competitive compression. As the market expands, so does the number of operators chasing the same real estate positions, the same instructor talent pools, and the same membership cohorts. The franchisees who lock in differentiated formats and high-traffic locations in 2025 and 2026 are positioning ahead of a wave, not catching up to one.
This dynamic is visible globally. Fitness Park, one of Europe's largest gym chains, is targeting over 400 clubs in its network and has announced 80 new openings planned for 2026. One of those openings is a 1,600 square meter facility near Lyon scheduled for July 15, 2026. The scale and pace of that expansion reflects the same underlying conviction: the window for securing strong real estate and format differentiation is open now, and it won't stay that way.
If you want a longer-horizon view of where this market trajectory leads, the analysis on the fitness market doubling by 2036 provides the structural context behind why operators are moving aggressively on footprint right now.
The Instructor Hiring Problem No One Talks About
Here's the friction point that sits underneath every embedded boutique expansion: instructor supply.
Reformer Pilates is a credentialed discipline. Certification programs for Reformer instruction in the US typically require 450 to 500 hours of training, and the pipeline of qualified instructors hasn't scaled at the same pace as demand from franchised studio operators. Club Pilates alone has over 700 locations in the US. Add in the boutique studios, the hotel fitness programs, and now embedded gym concepts, and you're looking at structural scarcity in instructor supply in many mid-size US metros.
Fit Fusion entering Denver with four simultaneous openings means they're hiring for all four locations at once. That creates immediate local market pressure on instructor compensation and availability. It also means the quality and consistency of the Pilates experience across four locations will depend heavily on their ability to train, retain, and schedule qualified staff. That's an operational capability, not just a real estate play.
Operators considering a similar model elsewhere should factor instructor hiring timelines into their pre-opening schedule. Trying to source and onboard Reformer-certified instructors in the 60 days before a club opens is too late in most markets.
What This Signals for Franchise Operators Broadly
The Fit Fusion rollout is a concrete stress test of a format thesis that more franchisees are starting to explore. The core question it's answering is whether a big-box membership base can be converted, at least partially, into boutique service revenue without requiring a separate real estate investment.
If the embedded boutique model works in Denver, the implications for multi-unit franchise operators are significant. It suggests a path to revenue diversification that doesn't require acquiring a separate brand or signing a new lease. It compresses the capital required to offer a premium service tier. And it creates a retention mechanism: members who are engaged in structured, instructor-led Reformer sessions are statistically less likely to cancel than members who use the main floor sporadically.
There are parallel diversification strategies worth watching in adjacent recovery and wellness categories. Mobile cryotherapy units are becoming a low-capital recovery revenue stream that some operators are adding to their club footprint, which suggests the embedded add-on model extends beyond Pilates into recovery services as well.
The broader consolidation trend in fitness and activewear also points to an industry reconfiguring around fewer, larger platform operators. Private equity activity in European fitness reflects the same structural logic: scale and format differentiation are becoming the primary defensible positions in a market where low-cost membership pricing has largely been commoditized.
Three Variables to Model Before You Commit
If you're a franchise operator evaluating whether the boutique-within-a-box format makes sense for your markets, here are the specific financial variables that will determine whether the model works for your unit economics:
- Per-square-foot revenue contribution: Compare the projected boutique studio revenue per square foot against your current open floor average. In most big-box gyms, open floor generates $8 to $15 per square foot annually in membership revenue allocation. A boutique studio running at 70 percent fill rates with $35 average class revenue can generate $80 to $120 per square foot. The spread justifies buildout cost if you have the demand.
- Instructor cost as a percentage of boutique revenue: Target instructor labor at no more than 35 to 40 percent of boutique session revenue. If your rate card and fill rates don't support that ratio, your buildout payback period extends materially.
- Main floor to boutique conversion rate: Model conservatively. Assuming 5 to 8 percent of your general membership base will convert to paid boutique participation is a reasonable baseline for year one in an established big-box location.
The Fit Fusion Denver experiment will produce real data on all three of these variables over the next 12 to 18 months. For the franchise operators watching from the sidelines, that data will be more valuable than any pro forma projection.
The boutique-within-a-box model isn't guaranteed to work at scale. But the structural logic behind it is sound, the market timing is favorable, and the operators moving now are the ones who will have the clearest view of what it actually takes to make it work.